This commentary was prepared for clients on October 5, 2026.
Stock prices marked time this quarter as investors adjusted to competing economic forces. The choppy quarter featured both negative and positive developments, including a combination of higher oil prices and rising interest rates amid a surprisingly robust economy.
The latest concern has been another spike in oil prices. The ongoing conflict involving Iran has disrupted normal energy flows through the Strait of Hormuz, creating renewed uncertainty about the global supply of crude. Crude oil briefly moved above $105 per barrel again during September before falling back into the low $90s at month-end. Higher energy prices matter because they can put renewed upward pressure on inflation at the same time that the economy remains quite strong. That combination has contributed to a sharp rise in interest rates. Hence, a choppy quarter for the stock market but we believe the outlook remains favorable for the remainder of the year.
Interest Rates: From Financial Repression To Normalization
The 10-year Treasury yield has crossed above the 5.3% mark, its highest level since 2002. We view the rise in interest rates somewhat differently from many of the market commentators you hear today. Following the Great Recession from 2009 to 2015, and again during the pandemic from 2020 to 2021, the Federal Reserve held short-term interest rates near zero to combat deflation and stimulate the economy. This prolonged period of ultra-low yields was often characterized as “financial repression”. The result was an unusual period of exceptionally low borrowing costs and very low returns available to savers and bond investors.
That era ended with the inflation surge following the Covid pandemic. Beginning in 2022, the Federal Reserve embarked on an aggressive rate-hiking cycle to bring inflation under control. While the Fed has a new chairman, Kevin Warsh, the broader trend has been toward a return to more historically normal interest-rate levels. Welcome to the old normal!
Our response throughout this low-rate environment has generally been to maintain a short-term bond ladder, which reduced the interest-rate risk associated with longer-maturity bonds. A shorter-maturity approach is less sensitive to rising rates than longer-maturity bonds, which declined in value when rates rose sharply beginning in 2022. As interest rates rose, maturing bonds in the ladder could be reinvested at higher yields. We believe this approach continues to provide a source of income and relative stability, in the current environment.
Importantly, however, the rise in yields is beginning to change the risk-versus-reward equation for fixed-income investments. For the first time in decades, we believe there is real value in high-quality bonds. With yields at current levels, they have become more compelling long-term investments. As yields have moved higher, we are increasingly interested in gradually extending maturities to capture what we believe are attractive yields for the years ahead.
A Strong Economy Keeps Rates Elevated
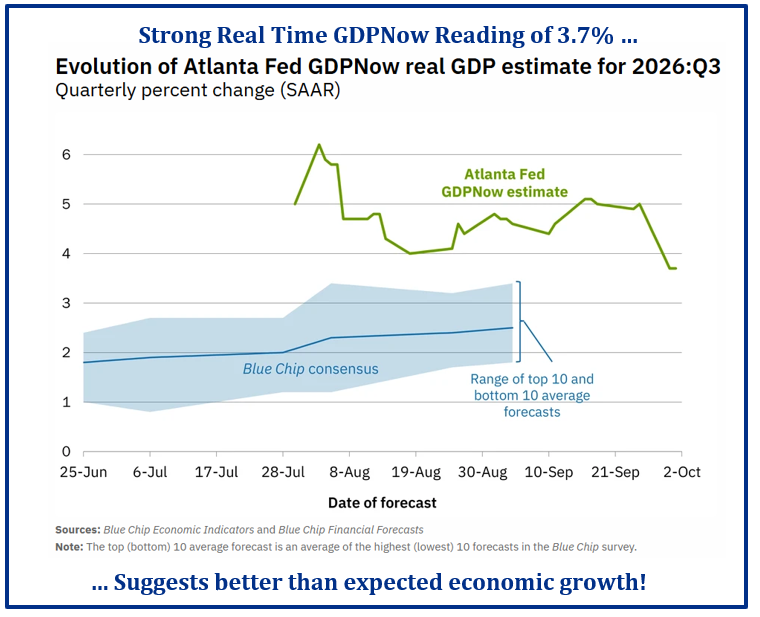
Another reason interest rates remain under pressure is that the economy continues to show considerable strength. For example, the Atlanta Federal Reserve’s latest GDPNow estimate is running at approximately a 3.7% annualized growth rate for the third quarter (as of September 30, 2026). GDPNow is an estimate rather than an official forecast, but it provides a useful real-time indication of the strength of the economy.
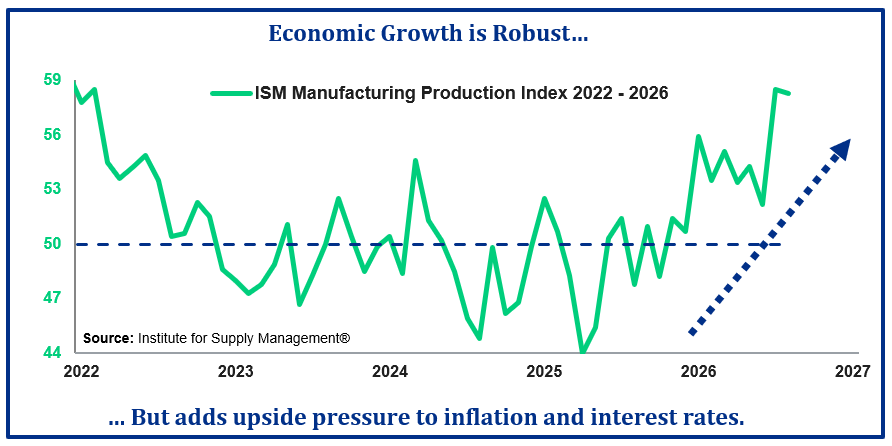
The latest Institute for Supply Management® Manufacturing Production Index data tells a similar story. The August reading (pictured below) showed one of the highest readings of U.S. business activity in more than four years, with strong growth in both services and manufacturing. At the same time, the survey showed renewed cost pressures, including higher energy prices. Put simply, we appear to still be in the inflationary portion of the business cycle: economic growth is strong, demand remains healthy, prices are rising, and interest rates are responding accordingly.
A Stealthy Stock Market Correction
This quarter the average stock has been more unsettled than the major indexes would suggest. The S&P 500 has been supported by a relatively small group of mega-cap growth companies, masking considerable weakness among the average stock. Beneath the surface, many stocks have already experienced meaningful corrections. For example, only about 20% of New York Stock Exchange (NYSE)-listed stocks were trading above their 50-day moving averages as of September 30, 2026—which we view as an indication of how widespread the weakness has become. Readings this low can be followed by strong rebounds.
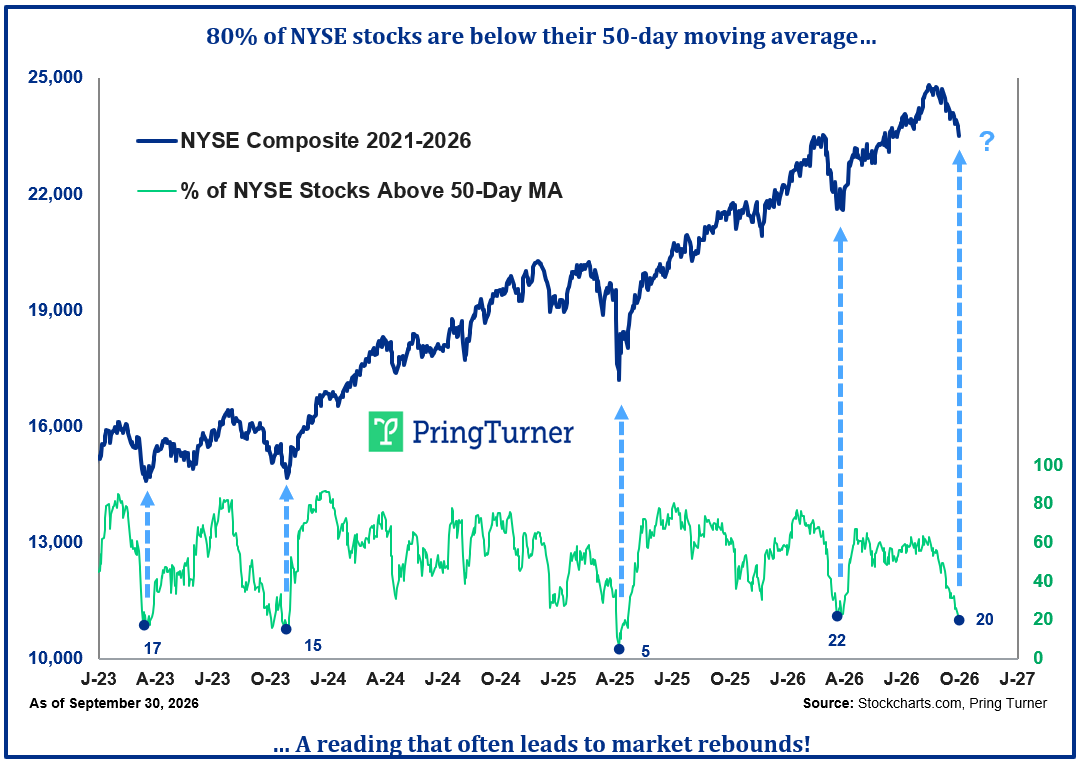
We would describe this behavior as a stealth correction—a market decline that has occurred broadly across individual stocks without producing a comparable decline in the S&P 500. That distinction is important. Markets do not always correct through a dramatic decline in the major indexes. Sometimes the adjustment takes place through time, rotation, and declining prices in stocks that had previously become extended. In our view, much of that adjustment may have already occurred.
At the same time, investor sentiment has become increasingly cautious as the daily news has focused on oil, Iran, interest rates, inflation, and the possibility of further market weakness. We believe this increasingly bearish investor sentiment, combined with the price reset that has already taken place beneath the surface, is creating a potentially more constructive setup for stocks as we move toward year-end.
Outlook Still Favorable
Our approach throughout this period has been to remain focused on the progress of the business cycle rather than react to every headline. The combination of strong economic growth, persistent inflation, and higher interest rates is typical of the later stages of the business cycle. It also creates opportunities. Higher bond yields have improved the outlook for fixed income, while the correction in many individual stocks could create opportunities to own some businesses at more attractive prices. Our overriding goal is to manage risk, maintain flexibility, and position client portfolios to take advantage of opportunities when they arise.
After a choppy quarter, we believe the investment landscape remains favorable. The reset in bond yields gives us an opportunity to capture meaningful income, while the broader correction in stocks is improving valuations in some areas of the market. We remain alert to the risks, but we also recognize that markets often pause and take a breather during ongoing bull markets. With that in mind, we enter the final quarter of the year with a constructive outlook.
On behalf of all of us at Pring Turner, thank you for your continued trust. As always, please feel free to contact us should you have any questions, or if your circumstances should change.